One Index Says Boom, Another Says Bust: Hong Kong’s Split-Personality Property Market Business

One Index Says Boom, Another Says Bust: Hong Kong’s Split-Personality Property Market

香港房地产释放两个相反信号。9月价格指数同比涨9.3%。同期住宅买卖合约同比跌15.6%。成交量比12个月均值低38%。价格在涨,市场在缩。这不是复苏,是幻觉。 官方数据确实支持价格上升。9月价格指数320.8,环比涨0.19%,同比涨9.3%。租金指数212.2,创历史新高。连续11个月上涨,同比涨6.2%。前九个月价格累计涨7%,租金累计涨5.8%。拆开看,大单位价格环比涨0.80%,小单位只涨0.16%。大户型拉动指数,小户型停滞。 成交量讲另一个故事。9月住宅买卖合约4,761份,环比涨18.5%,同比跌15.6%。交易金额46.8亿港元,同比微降0.9%。12个月移动平均成交7,682份,9月低38%。移动平均本身环比降0.5%。Knight Frank预测今年住宅价格涨8%-10%,但成交量不支持。“市场触底反弹”和“内地买家推动”的说法缺成交量支撑。租金创纪录看似利好收益率,但价格涨得快于租金。3.9%毛收益率实际约3.8%。扣掉管理费、差饷和空置成本,净收益率更低。至于办公楼跟随住宅的说法,同样缺量。 市场没有全面复苏。只有高端细分在重新定价,整体交易量在萎缩。如果成交量回不到移动平均以上,价格涨势缺乏基础。看成交量,别只看价格指数。这是判断香港楼市真实状态的指标。
More
A $24 Mug, Three Ways to Ship It, and the Math That Quietly Kills Most Sellers Business

A $24 Mug, Three Ways to Ship It, and the Math That Quietly Kills Most Sellers

Here is a test most cross-border sellers fail. Five hundred ceramic mugs, 1.2 kilograms each, retail at USD 24, made in Guangdong, sold into the United States in Q4 2026. Three routing options exist. The gap between the cheapest and the most expensive is larger than the entire gross margin on the product. Yet sellers keep choosing by reading rate cards. A rate card prices a unit. The actual decision is about a ratio. That mismatch is where margin dies quietly, and almost nobody notices until the quarter closes and the numbers refuse to reconcile. Take the Amazon stack first. CICC calculates the platform's aggregate take rate at 27.8% in Q2 2026. That bundles referral, fulfilment, and the now-mandatory advertising spend. At USD 24, that is USD 6.67 per unit, or USD 3,335 across 500 units. Add USD 4.20 ex works and USD 1.90 inbound sea freight, and total landed cost is USD 12.77. Gross margin: USD 11.23, or 46.8%. What 27.8% buys is Prime badging, returns handling, and zero operational headaches. What it costs is control. Inventory sitting in an Amazon fulfilment centre cannot easily move to a second channel, and fees change on Amazon's schedule, not yours. The 3PL stack is where sellers graduate and, at this volume, where they get hurt. The platform fee vanishes, replaced by a payment processor at 2.9%, roughly USD 0.70. Sounds great until the rest arrives. Pick and pack runs about USD 6.10. Storage adds USD 0.08 monthly. Then comes the killer: roughly USD 7,500 in fixed onboarding and warehouse minimums. Divided by 500 units, that is USD 15 per unit before a single parcel moves. Total cost lands at USD 28.66, above the retail price itself. The 3PL only crosses Amazon at around 10,000 units a quarter, at USD 13.40. Direct parcel from Shenzhen is the quiet survivor. After the de minimis exemption was suspended in 2025, low-value shipments now carry duty and entry processing. Budget USD 9.50 per unit for express delivery all-in. No US inventory, no warehouse, no fixed cost. Total: USD 14.40 per unit, leaving a 40% margin. Second cheapest of the three stacks, and the only one requiring zero upfront cash commitment. Two of three stacks demand you park inventory in America before selling a single unit. That is a cash decision disguised as a logistics decision, and it is exactly the one sellers skip when they shop for rates. The real dividing line is not volume. It is price per kilogram. At USD 24 for 1.2 kilograms, this mug sits at USD 20 per kilo, and at that density the platform stack wins on cost while losing on control. Sort your catalogue by that ratio and the choice stops being taste. Heavy and cheap belongs on Amazon, where the percentage fee stays small in absolute terms. Light and expensive can justify direct parcel. The middle ground, where founders romanticise owning the customer relationship through a 3PL, only works past roughly 8,000 units a quarter, when that USD 15 fixed burden shrinks to USD 0.94. So the next founder who brags about ditching Amazon for a 3PL at 500 units a quarter has simply not done the division yet.
More
Dream’s AI Knows What Got Built. It Doesn’t Know Why. Business

Dream’s AI Knows What Got Built. It Doesn’t Know Why.

The pitch rests on a contradiction. Elder says: "Our model actually understands what's within those walls. What materials are used, what the beams are made of, and how much weight they can support." They trained it on permit archives. Those archives record projects that were approved. Each file is an outcome that cleared a plan reviewer. The iterations that produced it are mostly absent. What the archive contains is a distribution of designs that passed. Not the reasoning that got any single design there. That is the industry anxiety. AEC work runs through licensed professionals who stamp drawings. Insurers ask how a design was produced. When model and engineer disagree, who owns the revision? The facts are specific. $17 million seed round. Andreessen Horowitz led, with SV Angel, XYZ and Zigg Capital participating. Founders Andy Elder and Arjun Mathur met as Stanford CS students. They spent a decade at Palantir. Elder led product design for 800 people building defense software. Mathur was a senior VP in commercial practice. Neither worked in architecture. The training corpus is 100 million square feet of building data from US permit archives. Mathur argues the industry regressed. "We've gone from dial-up internet to superintelligent AI, but our ability to build the physical world around us has actually decreased." Ten active projects in Texas and California. Kimberly Tan of a16z invested over a year ago. The commercial loop runs through plan review. Early customers use Dream to conceptualize designs and estimate costs. That is the front of the process. The end-game is a specific check. A building designed by the model that clears engineering review without a person redrawing it. Every project through plan review leaves a record. Those records will show whether the model's drawings needed an engineer to redraw them. Or only to sign them. If output arrives as BIM-native geometry with structure attached, the substitution story holds at concept stage. If it arrives as an annotated image, the value sits in the first client conversation. Ten projects is a sample. The answer comes through ordinary business.
More
Zest’s Text Thread Gambit: Why Your Credit Card History Just Became the Friend Group’s Most Valuable Data Point Business

Zest’s Text Thread Gambit: Why Your Credit Card History Just Became the Friend Group’s Most Valuable Data Point

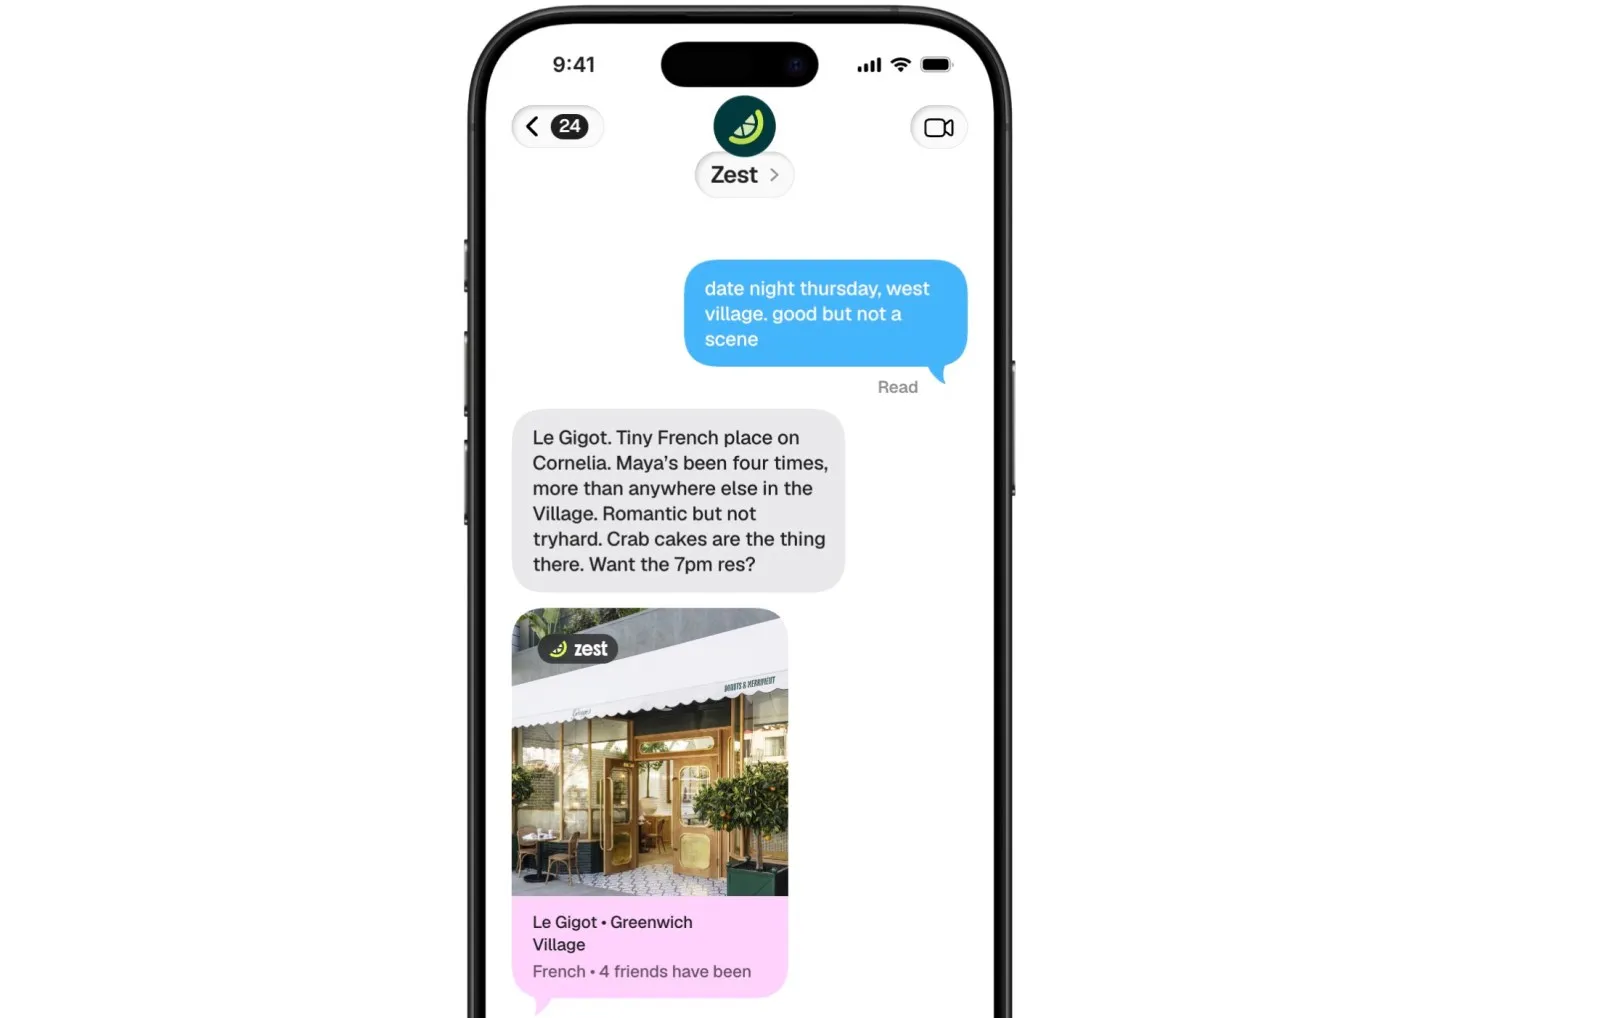
Zest just did something quietly audacious. They removed the app from the restaurant decision loop entirely and dropped their concierge agent straight into the group chat where actual decisions happen. The product isn't browsing anymore. It's text-based negotiation with your actual spending ledger as its only ground truth. Mario Gomez-Hall said the agent is the product now, and he meant it literally. You text the number, it answers from the dining histories of everyone in the thread, and suddenly the friction of opening yet another restaurant app dissolves into a conversation that was already happening. The original launch in November 2024 positioned Zest as a discovery tool powered by Plaid-connected credit card transactions. That was the first layer. This week's update added the concierge interface and real-time booking through OpenTable, Resy, and SevenRooms. The official story is convenience. The subtext is infrastructure play. Zest is building the data layer between your actual eating habits and restaurant inventory systems that nobody else touches. They raised $1.8 million in pre-seed from Alexis Ohanian at 776 and Steve Jang at Kindred Ventures to fund exactly this build-out. Several thousand users are already feeding the ledger. Here's what the press release won't stress enough. Card data tells you where someone paid and how much. It does not tell you what dish they ordered, whether the acoustics ruined the evening, or if the host made them feel unwelcome. Frequency masquerades as preference. The restaurant near your office gets visited because it's near the office, not because it's good. And the traveling diner problem remains unsolved. Zest names cross-city recommendations as a use case without explaining how the taste model actually transfers across geographies. That gap is real and it matters. Group thread dynamics introduce a different kind of friction. Blend tastes from linked accounts and the math works. Put four friends in a thread where only one linked their card and the model hits a wall. The launch materials do not explain how Zest handles that friend. Inference? Consensus override? Neutrality assumption? The booking dependency is equally thorny. Zest does not own table inventory. It operates as a pass-through to platforms that charge restaurants for reservations. The commercial agreement that determines who gets paid when a table fills will decide whether this feature survives or gets quarantined by the very systems it relies on. Gomez-Hall framed booking and ordering as the first revenue lines. Food ordering is coming next. But text messaging carries carrier registration costs in the U.S. and unregistered high-volume traffic gets filtered before it reaches a handset. Each message in a group thread burns a model call. A conversation that ends without a reservation is pure cost, not a lead. The interface itself forces narrowing. No map, no grid, no skim. Zest responds with one suggestion, a reason, a photo, and a booking link. It is a product shaped by its delivery channel, not the other way around. Instinct and Poke were already answering restaurant texts before Zest shipped this feature. The specialist argument is that a real spending ledger beats general assistant capability on this single task. That thesis holds for people who have already linked their cards. It collapses for the larger population that wants Saturday night's table and has never connected a single payment account. Zest delayed this launch for a full month to finish the booking path, which tells you where they believe the real value lives. The app is still there but the bet is clear. The thread is now the product. What happens when the ledger runs dry or the platforms pull the rug? That is the question nobody in the press release is answering.
More
110 Was Perfect. Minus 170 Was Reality. The Pentagon’s Cyber Grade Problem. Business

110 Was Perfect. Minus 170 Was Reality. The Pentagon’s Cyber Grade Problem.

The defense industry has a compliance paradox. Contractors post perfect self-assessed scores under NIST SP 800-171. Federal reviewers turn those numbers into liabilities. In June, LOGZONE settled with the government. A review put its self-reported score at minus 170. The Alabama contractor had posted a perfect 110. In September, Honeywell Aerospace agreed to pay over $2 million. The Justice Department alleged it failed to meet the same standard on one network. Neither company admitted liability. The gap between what companies claim and what they can prove is the real vulnerability. Self-assessments rely on the contractor's word. The signature behind it carries legal weight. But the evidence behind that signature is often missing. The scoring system is unforgiving. NIST SP 800-171 contains 110 security requirements. Assessors expand them into 320 objectives. They check each against documents, interviews, and tests. They score only what a company can show. The result goes to the Pentagon's Supplier Performance Risk System. A senior official signs an annual affirmation. The Defense Department suspended the second phase of its CMMC program in July. Self-assessments and SPRS scores remain in place. The government is trusting contractors to grade themselves. It checks afterward through False Claims Act enforcement. The failures are mundane. A System Security Plan describing retired systems. Controlled files on drives the plan never mentions. A posted score that doesn't reconcile with the plan. Evidence that exists but can't be produced on request. As Linda Cureton put it, "Those aren't technology failures. They're records failures." Muse Technologies bets that records, not tooling, are the fix. The firm manages federal records under National Archives standards. It has handled over a million case records. Cureton ran NASA's IT organization from 2009 to 2013. Her argument is simple. Assessors think like archivists. If it isn't documented, it didn't happen. Muse offers a free SPRS self-check and a free 60-minute score review. The paid engagement is a six-week CUI and AI Exposure Review. It maps where controlled information lives. It assigns each of 320 objectives a named owner and evidence source. It builds the file behind the annual affirmation. The review also documents what AI tools like Microsoft Copilot can reach. The client's total time commitment is under 10 hours. Muse guarantees every objective gets a named owner and evidence source. Or the client isn't invoiced. Muse doesn't certify. It sells no software, licenses, or managed services. The evidence it builds belongs to the client. Contractors must weigh a consulting fee against a $2 million settlement. Or a score that flips to minus 170. The ten hours is the number worth watching. Most of the evidence file is reconstruction. The guarantee covers ownership and sourcing. It doesn't cover what the assessor thinks.
More
A Schwab Insider Quoted 70% Failure Rates on a Podcast. I Did the Math He Hoped Nobody Would. Business

A Schwab Insider Quoted 70% Failure Rates on a Podcast. I Did the Math He Hoped Nobody Would.

Here is a pitch you have heard at every wealth conference for a decade. Rich families do not lose their money to bad portfolios. They lose it to bad governance, so they need a bigger platform, more services, and an adviser who becomes the hub of everything. In January 2026, Sam Kang, who runs Schwab Family Office, made exactly that case on the Barron's Advisor podcast with Steve Sanduski. He was candid and specific, which is rare. He was also arithmetically incoherent, which is telling. He claimed USD 124 trillion will change hands over the next two to three decades. In the same breath, he said USD 2 to 3 trillion transfers every year. Divide the first by the second. The horizon comes out at 41 to 62 years, not 20 to 30. For both numbers to be true, the annual flow would need to be roughly USD 4.1 trillion at 30 years, or USD 6.2 trillion at 20. Nobody on the call noticed. That silence is the story. Run through the rest of the figures and a pattern emerges. The 70% failure rate of wealth transfer by the second generation, the 13% and 3% survival rates at the third and fourth generations, the 700%-plus growth in ultra-high-net-worth households since 2011, the USD 17 trillion segment size, the USD 6 trillion held by multi family offices, the 6.6% independent RIA share. None of it came with a named source. The one figure that did have a source was the Family Wealth Alliance survey showing 70% of multi family offices now use hybrid or retainer pricing. In other words, the only number the industry bothered to verify is the one about how it charges. Everything about the customer is folklore. Even the fee illustration, 40 basis points on investments and 70 to 80 all in, was given as decoration. And across a forty-minute conversation about what ultra-high-net-worth families want, not a single family was quoted or described. Follow the money and the pitch explains itself. Kang sells custody and technology to advisers, so his revenue rises when advisers absorb more rich households onto a larger platform. A scary, unsourced 70% failure rate is the perfect sales instrument, because it converts a governance problem no one has measured into a service bundle someone can bill for. The retainer shift is the tell. Moving 70% of multi family offices off pure asset-based fees and onto hybrid pricing locks in revenue whether or not the wealth actually transfers. Ask for the footnote on that 70% failure rate the next time an adviser quotes it to you. There is not one.
More

The Grid Queue: Why 32 GW of Gulf Solar Is Stuck Behind a Wall of Transformers

By: Reginald Vance The Gulf signed 47 GW of solar. Only 14.8 GW reached the grid. That is a 32.2 GW gap. The gap is not a capital shortage. It is not a chip shortage. It is a grid connection queue. The queue is the binding constraint for 2026. Two record buildouts are running across the Gulf at the same time in 2026. The energy buildout and the AI data centre buildout are colliding over the same scarce grid connections. The solar farms are built. The AI data centres are planned. The grid is not ready. This is a physical hardware limit. The transformers, switchgear, and high-voltage cables are the real chips. They are in short supply. The queue is lengthening. Capital is not the issue. The money is there. The chips are there. The grid is not. This creates a peculiar market panic. Everyone is rushing to build, but the grid connection is the wall. The panic is not about demand. It is about the queue. The AI data centres need massive, constant power. Solar is intermittent. The grid must provide the base load. The grid must also absorb the solar. The grid connection is the interface. The interface is clogged. The queue is the clog. The clog is the constraint. The constraint is not financial. It is physical. The physical queue is the market panic. The panic is that 2026 will be a year of stalled buildouts. Not because of money, but because of the grid. The grid is the new chip. The grid is the new bottleneck. The bottleneck is the queue. The queue is the new power. The power is the constraint. The 2026 buildout is a race. The race is not about who has the most capital. The race is about who has the grid connection. The grid connection is the finish line. The finish line is the queue. The queue is the race. The race is the constraint. The queue is the new oil. The queue is the new gas. The queue is the new energy. The energy is the queue. The system is simple. You sign a solar agreement. You wait for a grid connection. The queue is long. The data shows 47 GW signed, 14.8 GW connected. That means over 32 GW is sitting in the queue. These are not idle projects. They are waiting for energized grid connections. The hardware components for these connections are the bottleneck. High-voltage transformers have lead times of years. Switchgear manufacturing is near capacity. The cable suppliers are booked out. This is the physical scaling limit. It is not a foundry issue for chips, but a foundry issue for grid equipment. The manufacturing base for this equipment is concentrated. There are only a few qualified suppliers. Their yields are the real fabrication node yields. The queue is the inventory. The buildout is constrained by the grid connection, not by capital. The capital is flowing, but it is stuck at the connection point. The supply chain for grid equipment is the new chip supply chain. The agreements for transformers are the new chip supply agreements. The foundry data is the transformer factory data. The yields are the transformer yields. The queue for a grid connection is the new backlog. The backlog is the constraint. The backlog is not about paperwork. It is about physical hardware. The physical hardware is the transformer, the switchgear, and the cable. The cable is a critical item. The high-voltage cable manufacturing is concentrated in a few plants. The plants are at full capacity. The lead time for a transformer is now measured in years. The queue is the result of this. The queue is the new reality. The new reality is that the grid connection is the gate. The gate is the constraint. The constraint is the hardware. The hardware is the transformer. The transformer is the chip. The chip is the queue. The queue is the market. The market is the queue. The queue is the transformer. The transformer is the gate. The gate is the constraint. The constraint is the queue. The transformer is the new chip. The switchgear is the new chip. The cable is the new chip. The chip is the queue. Cash flow efficiency is the key. The capital is committed, but it is trapped in the queue. This creates a cash flow problem for developers. The solar farms are built, but they cannot generate revenue until they connect. The data centres are powered by gas turbines, but they need grid backup. The grid connection queue is the cash flow bottleneck. This will lead to consolidation. The grid equipment vendors are the gatekeepers. They are in a position to raise prices and allocate capacity. The endgame is that the grid connection queue will determine who wins in the Gulf energy and AI buildout. The developers with the strongest grid connection agreements will dominate. The rest will be stuck in the queue. This is a hardware vendor consolidation scenario. The grid equipment makers are the new chip suppliers. Their capacity is the binding constraint. The cash flow efficiency is defined by the queue. The developers who get in line early will have the best cash flow. The ones who come late will face a cash flow crunch. The consolidation will happen among the developers. The ones without grid connections will be acquired or will fail. The hardware vendors will consolidate their pricing power. The endgame is a few dominant grid equipment suppliers controlling the buildout pace. The pace of the buildout will be set by the grid connection queue. The queue will not be solved by capital. It will be solved by time. The time is years. The 2026 buildout will be slow. The slow buildout will be the reality. The reality is that the queue is the market. The market is the queue. The queue is the new supply chain. The supply chain is the constraint. The constraint is the grid connection. The grid connection is the new chip. The new chip is the transformer. The transformer is the bottleneck. The bottleneck is the queue. The queue is the endgame. The endgame is the consolidation. The consolidation is the queue. The queue is the cash flow. The cash flow is the constraint. The constraint is the endgame. The cash flow is the queue. The queue is the cash flow. The consolidation is the endgame. The endgame is the consolidation. Author bio: Reginald Vance, a venture partner specializing in semiconductor valuation and advanced materials, has spent a decade tracking hardware supply chains and capital allocation in the tech manufacturing sector.
More

The Robot Illusion: Why Japan’s Tech Fix Failed to Fill the Care Gap

By: Dominic Cole Japan bought a mountain of machines. It still cannot find enough hands. For over a decade, the Japanese government and private sector have poured capital into care robotics, viewing automation as the primary counterweight to a shrinking demographic. The assumption was simple. If we lack bodies, we add circuits. The reality is messier. The crisis persists not because the robots failed technically, but because the labor deficit is structural, not just operational. We are witnessing a gap between technological capability and socioeconomic integration. The machines are there. The workforce is not. Four widely repeated claims about Japan’s eldercare crisis in 2026 require a hard look. The first claim is that automation has solved the staffing shortage. The data says otherwise. While robot deployment has increased, it correlates with specific, narrow tasks. It does not correlate with total care hours. The second claim is that immigration will plug the gap. Policy restrictions and language barriers keep this channel narrow. The third claim is that wages have risen enough to attract domestic workers. Inflation has outpaced salary growth in the care sector. The fourth claim is that demand for care will stabilize. Aging demographics ensure the opposite. Demand is compounding. The arithmetic is brutal. A care facility cannot simply swap a human for a machine across all functions. Robots can lift. They can fetch. They cannot navigate the emotional complexities of dementia care with the same nuance a human provides. The industry subtext is clear. We are automating the physical load, not the relational care. This creates a new category of labor. Staff are needed to program, monitor, and maintain the devices. It is a different skill set. It is not a direct substitute for the nurses and caretakers who are retiring. The supply chain of human capital is broken at the recruitment stage. We must stop treating technology as a demographic panacea. The end-game for Japan is not a fully automated society. It is a hybrid model where humans handle the high-empathy tasks and machines handle the heavy lifting. This requires a massive retraining program. It requires immigration policy that actually functions. It requires wage structures that reflect the true cost of labor. Until those levers are pulled, the robots will sit in the corners of care homes. They are impressive tools. They are not a solution. The crisis remains because the root cause is social, not mechanical. Author bio: Dominic Cole, an independent demographer specializing in state-capacity modeling and labor trends.
More

The Numbers Don’t Add Up: Why Thailand’s Two PromptPay Truths Are a Trust Problem, Not a Math Problem

By: Ethan Gallagher Thailand's payment infrastructure is running on two different realities. That is not a metaphor. The Bank of Thailand and National ITMX are both publishing official totals for PromptPay, and they disagree by 6.2 percent. In a system moving billions of baht daily, a discrepancy that clean and that persistent is not a rounding error. It is a structural signal. Something about how transaction volume gets defined or attributed is broken. And whoever controls the definition controls the narrative. The fact that matters most came out in May 2026. National ITMX published its own tally for the month: 2.38 billion transactions, carrying a total value of 4.45 trillion baht. That figure traveled. It showed up in press coverage, investor briefings, and regulatory discussions without apparent scrutiny. The central bank, however, was reporting a different number. Two calibers. Five figures that do not reconcile. The NITMX release was internally consistent. The gap lived entirely in the relationship between the two institutions' published datasets. That is the kind of gap that does not close on its own. What this actually reveals about Thailand's payment architecture is more interesting than any single headline number. PromptPay is not a single proprietary platform. It is a public utility layered over private banking infrastructure, routed through NITMX as the switching operator, and overseen by the central bank as the authority. When two official bodies produce different totals for the same system, you are looking at a definition problem, not a data-entry problem. One institution may be counting gross throughput. The other may be counting net settled value. One may include retry transactions. The other may filter them out. The 6.2 percent divergence suggests the两套 counting methodologies are fundamentally misaligned, and the public is being sold two different versions of the same truth. This is not an academic dispute. Payment volume statistics shape investment decisions. They influence policy. They determine whether PromptPay is celebrated as a continental success story or questioned as an overpromised rollout. When the central bank and its switching operator publish incompatible figures, trust does not split evenly between them. It evaporates entirely. Market participants stop knowing which number to bet on. Regulators lose their anchor. The supply chain landscape for fintech in Thailand just got a lot murkier, and no one is asking the right question yet. Author bio: Ethan Gallagher, a Silicon Valley Hardware Architect and Infrastructure Strategist with deep expertise in payment routing systems and emerging-market fintech deployment.
More

The $0.15 Rebellion: Cognitum One’s MetaHarness Is About to Turn Frontier Models into Cheap Commodities

By: Oliver Hawthorne The AI industry is built on a pricing illusion. Developers are trapped in a silent panic. Every agent run, every tool call, every complex reasoning step translates directly into a massive, unpredictable bill. Founders are terrified that a single viral user loop will bankrupt them before they even find product-market fit. The big labs enjoy record margins, charging developers a premium for access to their black-box intelligence. But this house of cards is built on a fragile assumption. Developers have no choice but to pay. That anxiety just found its ultimate expression in a quiet announcement from Reuven Cohen. He didn't just launch a product. He launched a pricing rebellion. By open-sourcing the agent harness, he is threatening to strip the model of its billing entirely. The model is no longer the billable unit. The harness is. And if the harness is free, the entire premium pricing model of the frontier labs collapses overnight. This is the core contradiction that the industry has been ignoring while pouring billions into compute. The anxiety is no longer about model quality. It is about billing survival. The traditional commercial loop assumes that intelligence must be expensive. It assumes that developers will pay anything for access to the latest weights. But the reality of modern software engineering is different. Agents are not just calling the model once. They are calling it dozens of times in a single user session. They are executing complex chains of thought. They are calling external APIs. Each of these steps incurs a token cost. The developer is left holding the bag. The pricing model is broken. It punishes complexity and rewards the labs for every failed hallucination. Cohen saw this broken loop. He decided to break it entirely. His open-source factory is the hammer that will smash the pricing glass ceiling. The industry is watching in silence. The panic is real. The pricing illusion is finally bursting. The developers are waking up. They are realizing that the model is not magic. It is just code. Code that can be run anywhere. The panic is turning into anger. The anger is turning into action. Cohen's release is the catalyst. It gives developers the tools to fight back. The pricing cartel is on the defensive. The battle for the agent stack has begun. Let us look at the facts. Reuven Cohen and Cognitum One just shipped MetaHarness. The release landed alongside GitHub Universe 2026. This is not just another software library. MetaHarness is an open-source factory for agent harnesses. The concept is remarkably simple. You point it at a repository. It spits out a branded harness you can deploy immediately. The critical shift lies in how billing is handled. Cohen made the model irrelevant to the bill. The headline mentions a $0.15 bug fix. This is not a metaphor. It represents the actual cost of raw model inference when decoupled from the expensive orchestration and billing layers of the labs. When a developer uses MetaHarness, the model becomes a commodity. The billing is no longer tied to expensive, proprietary API calls. It is tied to the harness itself. The harness manages the state, the tool calls, the retries, and the error handling. The model is just an engine. A cheap, replaceable engine. The $0.15 bug fix proves that the model's actual contribution to the task is trivial. The value is in the orchestration. The open-source community has just seized that orchestration layer. The facts are clear. The pricing cartel has lost its lock-in. But the technical implications go deeper. The harness is not just a billing wrapper. It is a full-stack execution environment. It handles the context window management, the token caching, and the prompt optimization. It abstracts away the underlying model entirely. The developer does not need to know if they are calling GPT, Claude, or a local Llama model. The harness handles the routing automatically. It chooses the cheapest and most reliable model for each specific sub-task. This dynamic routing is what makes the per-token pricing of the labs unsustainable. If the harness can route 80 percent of simple queries to a cheap, local model, the developer's bill drops by ninety percent. The $0.15 bug fix is a symbol of this efficiency. It shows that the model is just a utility. The real work is done by the open-source orchestration layer. The labs are left with no leverage. The facts are undeniable. The open-source movement has just won a major battle against proprietary lock-in. This is a massive victory for the developer community. It restores choice to the engineer. They are no longer hostage to a single vendor's pricing whims. They can choose the best model for the job. They can optimize for cost, latency, or privacy. The open-source harness acts as a neutral mediator. It ensures that the model remains a commodity. What does this mean for the commercial loop. The loop is changing. The developer no longer calls the API directly. The developer calls the harness. The harness handles the routing, the caching, and the fallback logic. The lab is reduced to a utility provider. A commodity engine behind the scenes. The end-game is clear. The value is shifting away from model creation and toward agent orchestration. Labs that cling to per-token pricing will watch their developer base evaporate. Startups will choose the open-source path. They will run their agents on cheap, local models. They will bypass the expensive APIs entirely. The $0.15 bug fix is the tipping point. It shows that the model is not the bottleneck. The orchestration is. My practical recommendation to any startup founder is simple. Stop paying the premium API tax. Build your own harness using open-source tools. Focus your engineering resources on the agent logic, not on prompt engineering for expensive black boxes. The era of per-token pricing is over. The next billion-dollar company will not be built on a proprietary model. It will be built on a smart, open harness that makes the model invisible to the bill. But the shift has wider implications for the entire enterprise software market. Large corporations are currently spending millions on custom agent integrations. They are locked into specific vendor ecosystems. MetaHarness offers them an escape route. It allows them to standardize their agent infrastructure across all departments. They can deploy a single, branded harness that works with any model. This reduces their dependency on any single vendor. It gives them negotiating power. The labs will be forced to compete on price and performance, not on proprietary lock-in. The commercial loop will become transparent. The developer will pay for successful outcomes, not for raw token usage. This is the ultimate end-game. The model becomes a utility. The harness becomes the product. My recommendation to enterprise CTOs is to evaluate open-source orchestration immediately. Do not sign long-term contracts with proprietary model providers. Build your own agent layer. Protect your margins. The pricing cartel is crumbling. The future belongs to the orchestrators. The future of AI is not about who trains the biggest model. It is about who builds the most resilient, efficient, and open orchestration layer. The labs that fail to adapt will become irrelevant. The orchestrators will define the next decade of software. The pricing cartel is crumbling. The future belongs to the orchestrators. Author bio: Oliver Hawthorne, a principal correspondent permanently stationed at an international technology review, covering the intersection of software engineering, infrastructure, and corporate strategy. He has spent years analyzing the economic and technical shifts that redefine the global developer landscape.
More

The Death of the Case: Why ESR Is Betting Your Next Purchase is a Cable

By: Ethan Gallagher Accessory makers have long been treated as second-class citizens in the Apple economy. They chase the new phone. They copy the mounting system. They race to the bottom on price. ESR just made a different bet. The Shenzhen company launched its iPhone 18 Pro collection today. It has two halves. Protective cases and cables. But the headline is not the case. The headline is the cable. This is a sharp departure from the standard playbook. Usually, the case gets the glossy marketing. The cable is an afterthought, a commodity item sold to justify shipping costs. ESR is flipping the script. They are positioning the connector as the primary profit center. The case is the Trojan horse. It gets the user into the ecosystem. The cable is where the margin lives. This is not just a product launch. It is a statement of intent about where value resides in the peripheral supply chain. Look at the industry subtext. Most brands rely on case customization for retention. A user buys one case, then maybe a second. That is it. The cable is a one-time purchase, often replaced every two years. By elevating the cable, ESR is creating a recurring revenue stream disguised as a single accessory. They are betting that users will pay a premium for faster charging or higher durability. This shifts the power dynamic. The case becomes the entry point. The cable becomes the lock-in. It is a subtle but significant change in how these vendors approach the Apple loyalist. The supply chain landscape is shifting. Component costs for high-speed connectors are rising. Apple is tightening its certification requirements. ESR is moving faster than the mid-tier brands. They are leveraging scale to absorb the certification costs. This is a blunt assertion. The accessory market is consolidating around a few players who can fund the compliance. ESR is playing the long game. They are not just selling plastic. They are selling confidence in a connection. The rest of the market will have to follow or be left on the sidelines. Author bio: Ethan Gallagher, a Silicon Valley Hardware Architect and Infrastructure Strategist, specializes in analyzing supply chain dynamics and hardware market shifts.
More

The Three-Way Split: Why Asian AI Tutors Are Fracturing the Global EdTech Model

By: Elena Rostova The phrase "AI in schools" has become a smokescreen for three completely different industrial strategies. In 2026, the Chinese-speaking regions of Asia are not building one market. They are building three distinct machines. Singapore is deploying a centralized, state-curated assistant known as SLS. Hong Kong is issuing per-school grants, betting on localized flexibility. Taiwan is running an adaptive platform, letting algorithms reshape the curriculum in real-time. Ask the ministries what they are doing, and each will claim they are improving literacy. The reality is far more granular and divergent. Singapore’s SLS assistant is a top-down infrastructure play. It functions less like a chatbot and more like a distributed administrative nervous system. The state controls the input, the guardrails, and the learning objectives. Teachers access a unified interface. Data flows upward to the ministry. This is a closed loop. It prioritizes consistency and compliance over individual variability. The "AI" here is a tool for standardization, ensuring that every student in the system receives the same high-quality feedback mechanism, regardless of their specific school location. It is a centralized command-and-control model wrapped in educational language. Contrast this with Hong Kong’s approach. There is no single platform. Instead, the government provides a grant to individual schools. Each institution chooses its own AI tutor vendor, its own integration path, and its own pedagogical model. This creates a fragmented marketplace. One school might use a logic-heavy reasoning engine. Another might prioritize creative writing feedback. The data does not centralize. It silos. This model bets that local adaptation beats state uniformity. It risks inequality between well-funded and under-funded districts, but it fosters innovation at the vendor level. Schools become the pilot zones for a competitive AI hardware and software market. Taiwan takes the third path. Their adaptive platform is the most aggressive. It does not just deliver content; it restructures the curriculum based on student performance in real-time. If a student struggles with fractions, the system reshapes the next week’s syllabus. If they excel, it accelerates the pace. This is a feedback loop that changes the input. It is less about delivering a static answer and more about dynamic course correction. The platform learns from the teacher’s interventions and the student’s hesitation. It is a closed-loop adaptive system that treats education as a continuous optimization problem, not a fixed syllabus. These are not variations of the same product. They are three different industrial logics. Singapore sells stability. Hong Kong sells choice. Taiwan sells adaptation. For global edtech investors, this means you cannot build a single product for "Asia." You must build three separate products for three different regulatory and cultural environments. The SLS assistant is a government utility. The Hong Kong grant model is a B2B marketplace. The Taiwan platform is a B2C adaptive service. If you are planning to enter these markets, do not assume a unified demand. The success of a centralized SLS model will fail in a fragmented Hong Kong district. The adaptive flexibility of the Taiwan platform will be rejected by a Singapore ministry seeking strict curricular alignment. The end-game is not a winner-takes-all scenario. It is a bifurcation of the tech stack. You will see specialized vendors emerging for each region. The SLS vendor will focus on compliance and integration with state databases. The Hong Kong winners will be marketing-heavy, customizable packages. The Taiwan leader will be a deep learning firm obsessed with algorithmic precision. These are three separate races with different rules, different judges, and different prize money. Ignore this split, and your product will be irrelevant in two of the three markets. Author bio: Elena Rostova, a public policy expert specializing in compliance assessments for governments or sovereign wealth funds, focusing on regulatory fragmentation in the Asia-Pacific tech sector.
More

The Agentic AI Mirage: Why Supply Chain Planners Still Trust Their Gut Over the Machine

The agentic AI pitch filling conference halls has a serious blind spot. It promises autonomous agents that will rewrite supply chain planning overnight. Yet the people actually running those plans, the ones sitting on mountains of real-time data, still freeze when a disruption hits. That freeze is not a technology problem. It is a trust problem. The tools generate insight. The planners still make the final call using a gut instinct and a spreadsheet. Until that gap is closed, agentic AI remains a solution in search of a user. The numbers and case studies in the latest industry release highlight the disconnect. Teams have data feeds streaming from suppliers, ports, and freight forwarders. They have dashboards that flag risks in seconds. When the next geopolitical shock or port closure hits, they still revert to manual processes. They pull up the old spreadsheet and make phone calls. The software predicts a scenario. The planner overrides it. This is the core contradiction behind the current agentic AI wave. Vendors claim the technology is ready for autonomous decision-making. Planners have seen enough broken promises to know the system cannot be trusted without supervision. The commercial loop here is straightforward. Agentic AI vendors need to prove their systems can do more than generate recommendations. They need to show that a planner can trust the agent to execute a course of action without constant hand-holding. That requires a fundamental shift in how these tools are built. The agent must not only propose a reroute or a supply adjustment. It must explain its reasoning in a way that aligns with the planner's own mental model. If the agent cannot articulate why a decision is sound, the planner will never cede control. The industry will remain stuck with expensive automation that produces analysis no one acts upon. The end-game for supply chain software is not about more data or faster algorithms. It is about closing the gap between what the machine recommends and what the human decides. The first vendor to solve that trust equation will capture the market. The rest will sell dashboards that get opened once a week. The landscape is shifting toward a reality where the planner becomes a supervisor of agents rather than a data entry clerk. But that only works if the agents earn the right to act. Until then, the industry is just simulating intelligence while the real decisions stay trapped in human heads.
More

Scarcity by Design: Hong Kong’s 10,000-Permit Cap Is a Trap for Everyone

Hong Kong's Transport Department has a number that nobody disputes. Personalized point-to-point demand runs at 880,000 passenger journeys a day. But the department just capped ride-hailing at 10,000 permits. That's a massive gap. And 30,000 drivers are already active. Two-thirds of the driver pool gets locked out. The five-year permit class compounds the problem. It freezes the cap for half a decade. No dynamic adjustment. No quarterly review. Just a fixed ceiling. This is not a market correction. It's planned scarcity. The industry feels it instantly. Platform operators see expansion plans collapse. Drivers see income routes close. Passengers see wait times stretch. The math is brutal. Ten thousand vehicles cannot serve 880,000 trips a day. A single driver handles maybe 20 trips per shift. That's 200,000 trips a day at best. The rest goes unserved. Or it goes to unlicensed operators. The anxiety is real. This is a structural shock. It's not a niche concern. The cap is a policy choice. The department surveyed the market. It knows the demand. It knows the supply. It chose to suppress supply. The 10,000 figure is arbitrary. There's no economic logic. It's a political number. It's a political compromise. The result hurts everyone. Drivers lose. Passengers lose. Platforms lose. Only the informal market wins. Consider the driver's perspective. A full-time driver in Hong Kong earns a living from these trips. The cap means many will lose their source of income. Some will try to join the informal market. That means unlicensed driving. That's illegal. The government is pushing drivers into illegality. That's not a policy. That's a trap. The driver doesn't get a license. He gets a choice. Drive illegally or leave the industry. That's the anxiety. Let's examine the raw data. The Transport Department's survey is the anchor. It puts the territory at 880,000 passenger journeys a day. That's for personalized point-to-point demand. It's a rigorous data collection exercise. Nobody disputes it. The department uses it. Now the active driver count. 30,000 drivers are active. That's the ride-hailing driver pool. The permit cap is 10,000. That's for ride-hailing vehicles specifically. So the cap is below demand. It's below current supply. The five-year permit class is separate. It fixes the cap for five years. No review. No adjustment. Hard ceiling. The permit class has requirements. Vehicle age. Driver background. Insurance. Standard stuff. But the cap is the killer. It's a supply-side constraint that ignores demand. The ratio is 88 trips per vehicle per day. That's impossible. One vehicle can't do 88 trips. Physically impossible. So the cap is a demand suppression tool. Not a supply management tool. The geography matters. Hong Kong is dense. The urban core is compact. Demand concentrates in Kowloon and Hong Kong Island. The 880,000 trips cluster in peak hours. They cluster around business districts. The cap doesn't address this. It reduces the total fleet. Wait times spike. Surge pricing spikes. The passenger experience degrades. The department's data says demand is there. But the policy says supply is limited. This is a fundamental mismatch. The policy isn't designed to solve a problem. It's designed to satisfy a constituency. That's the uncomfortable truth. Let's also consider the cost side. Permits are not free. The government will auction them. Or it will issue them through a lottery. Either way, the permit has value. In a market with 30,000 drivers and 10,000 permits, the permit price will be high. That's basic economics. The drivers who get permits will pass the cost to passengers. Fares will rise. The government might argue that permits keep quality high. But they also keep prices high. The survey doesn't measure permit value. It measures trips. The trips are there. The permits are not. Now the commercial loop. Ride-hailing is a two-sided market. Supply is drivers. Demand is passengers. The cap restricts supply. So the loop tightens. With 10,000 permits, platforms field only 10,000 vehicles. That's a fixed asset base. The only way to grow revenue is to raise price per trip. Surge pricing becomes the norm. But surge pricing suppresses demand. Total trips might drop. Platforms will fight for remaining demand. They'll compete on service quality. Not on price. The market will bifurcate. A licensed premium segment emerges. It serves high-income passengers. The mass market gets left behind. They take public transport. Or they use unlicensed services. The unlicensed sector grows. The government will crack down. That's the end-game. A predictable cycle. The cap creates scarcity. Scarcity creates a black market. The black market creates enforcement problems. Enforcement creates costs. This is a losing loop. The industry doesn't need a cap. It needs a dynamic supply model. It needs a permit system that tracks demand. It needs a review mechanism. But the government chose the static route. So the outcome is predictable. The cap will fail. It will be lifted under pressure. Or it will create a two-tier market nobody wants. The best case is a review in two years. The worst case is a decade of stagnation. The industry should push back. It should present the data. It should show that 10,000 is not enough. The 880,000 number is real. The department has the data. It just needs the will to use it. The commercial loop has another layer. Platforms will adapt. They'll shift to premium services. They'll push for higher take rates. They'll invest in autonomous vehicles. That's the long-term play. If permits are fixed, the only way to scale is to remove the driver. So the cap accelerates autonomy. That's perverse. The cap was designed to limit supply. But it pushes platforms toward driverless fleets. In five years, the permit class expires. By then, autonomous vehicles might be ready. The cap becomes irrelevant. That's the industry end-game. It's not about drivers. It's about the technology curve. The government is managing a 2025 problem with a 2015 tool. It won't work.
More

Why the UAE’s AI Push Is Stalling on the Boring End: The Trade License Trap

Everyone is talking about the big picture. Sovereign GPUs. Open-source giants. National digital identities. But I just spent the last hour looking at a trade license renewal application in Dubai, and it looks like a glitch from 1999. The task is simple. A distributor wants to add two activities to an existing license. The application arrives. The system chokes. It is not a lack of compute power. It is a lack of semantic grounding. The models are smart. The workflows are dumb. This is where the real friction lives. ’s recent breakdown highlights four models. Jais. Falcon-H1 Arabic. K2 Think. Copilot. They are being run against three Abu Dhabi government workflows. These are not toy datasets. These are live bureaucratic pipelines. The tests use Arabic benchmarks that stand in for real-world outcomes. The official narrative is progress. The subtext is stagnation. The models can generate text. They cannot navigate the labyrinth of permit logic. A renewal is not a creative writing exercise. It is a state machine transition. If the model does not understand the dependency chain between a new activity and the old license, it fails. The benchmarks measure fluency. They do not measure functional accuracy in high-stakes administrative tasks. The industry subtext is stark. Governments are buying hardware. They are building clusters. They are hiring researchers. But the software layer is disconnected from the actual user intent. A distributor in Dubai does not care about parameter counts. He cares if the system knows which fees apply when he adds activity two. The official release claims these models are ready. The data says they are brittle. The workflows are rigid. The language is specific. The models hallucinate when the context shifts slightly. This is not a hallucination of fact. It is a hallucination of process. The gap between "generating Arabic text" and "executing a government procedure" is a chasm. Nobody is bridging it. The benchmarks are too high-level. They do not capture the granular, transactional nature of public service delivery. The supply chain for sovereign AI is broken at the application layer. You can have the best chips in the region. You can have the largest models in the Middle East. It does not matter if the API integration is broken. The government does not need a chatbot. It needs a logic engine. Until the models stop trying to sound like humans and start acting like machines, the deployment fails. The money is flowing. The infrastructure is rising. But the value is stuck in the pipe. The next billion dollars will not be spent on bigger models. It will be spent on fixing the plumbing. The hardware strategy is sound. The software strategy is still a work in progress. And it is not close to done.
More

The $166 Billion Tariff Refund Trap: Why America’s Supply Chain Isn’t Getting Its Money Back

The United States just offered a $166 billion IEEPA tariff refund. The numbers sound generous. The reality is messier. The money does not flow to the companies that actually felt the price pain. It stops at the importer of record. That single legal designation determines everything about who gets compensated and who walks away empty-handed. The portal itself tells the story. According to at AsiaPresswire, the system asks for one specific thing. It does not want your receipt. It does not want your contract. It does not want proof that you absorbed the cost into your margins. It asks for a list. The data behind this process is stark. There are 20,184 approved claims sitting in an unpaid queue. Thousands of applications have cleared the first hurdle. None of those dollars have moved. This structure rewards whoever files the customs paperwork, not whoever bears the economic hit. A German machinery manufacturer selling to a Texas distributor did not pay the tariff. The Texas company did. The refund goes to Texas. The German firm cannot touch it. It cannot claim standing it never held. The law treats the importer of record as the sole beneficiary regardless of where the commercial cost actually landed. The supply chain consequences are quiet but damaging. Foreign manufacturers who raised prices to offset tariff costs will see nothing returned. Their American partners who absorbed the hit get the check. This creates immediate tension between trading partners who signed agreements assuming shared risk. Distributors now hold leverage they did not anticipate. They can keep the refund and renegotiate terms or simply walk away from commitments that no longer make financial sense. What happens next depends on how long these 20,184 approved claims stay in limbo. Companies that already factored a refund into their planning are operating on promises. Manufacturers who priced higher to stay solvent are watching their American clients collect money they never expected to see. The structural gap between legal standing and economic reality will force a reckoning in procurement contracts worldwide. Every party will rewrite their tariff clauses before the next round begins.
More

The Last Manual Entry in Construction: Why HCSS Just Made Motive Relevant Again

Contractors are still sitting in cabs at midnight, punching engine hours into spreadsheets by hand. This is not theoretical. This is the daily reality at worksites across North America. You have diesel trucks idling next to excavators. Both machines log fuel. Both need maintenance scheduling. Neither talks to the other. The data sits in three different systems. Someone has to type it all in. HCSS announced it is connecting its Fleet product to Motive. That is the official line. What this actually means is that the manual bottleneck contractors have accepted for years is finally getting patched. Fleet tracks equipment. Motive handles video telematics and driver monitoring. They were never designed to speak the same language. Now they will. The integration closes a gap that has existed since anyone started trying to digitize construction site operations. Here is what the press release does not say. The real cost of this friction is not the typing. It is the wrong decisions made from incomplete data. When fleet managers cannot see engine hours alongside real-time video evidence of operator behavior, they are guessing. They schedule maintenance too early and waste parts. They schedule it too late and suffer breakdowns. Mixed fleets create compound confusion because a dump truck tells a different story than a skid steer. The paperwork multiplies. The errors multiply faster. What HCSS is doing here is not revolutionary technology. It is mundane systems plumbing. But that is precisely why it matters. The construction industry runs on software that was never built to integrate. Every major vendor solved their own island problem. Fleet tracking went to one provider. Telematics went to another. Payroll went to a third. No one wanted to build the connectors. So contractors built them themselves with spreadsheets and tribal knowledge. That era is ending. Not because a new AI tool appeared. Because someone finally decided to wire the systems together. The supply chain implication is straightforward. When equipment data flows automatically between platforms, you stop losing money on missed maintenance windows. You stop overpaying for idle machines. You stop paying for fuel theft that no one caught because the numbers never crossed paths. This is not about being smart. It is about being connected. The contractors who adopt this integration first will have cleaner books and tighter margins. The rest will keep doing the math by hand until they get it wrong.
More

Three Numbers Walk Into a Bar: Why Nobody Can Actually Measure Southeast Asia’s Ecommerce Market

Ask three credible sources how big Southeast Asian ecommerce was in 2025 and you get three answers. Not close answers. Not answers that bracket a plausible range and agree to disagree. You get $157.6 billion, $185.5 billion, and $191 billion, each presented with the quiet confidence of an audited figure, none of them reconciled against the others. That gap, roughly $33 billion wide between the floor and the ceiling, is larger than the entire ecommerce market of most countries on earth. And the industry treats it as a rounding inconvenience. Investors quote whichever number suits the pitch deck. Founders cite whichever one makes their penetration story look best. Nobody asks why the denominators differ, because asking would be awkward for everyone at the table. Start with the most conservative figure. Platform GMV came in at $157.6 billion. This is the number built from what the major platforms actually transact, the checkout value flowing through Shopee, Lazada, TikTok Shop, and their regional peers. It is the cleanest definition and the smallest result, which tells you something important. The moment you widen the lens beyond formal platform checkout, the market inflates fast. GMV methodology is disciplined. It excludes a great deal of commerce that plainly happens online but never touches a platform's payment rails. That exclusion is not a flaw. It is a choice about what counts. Then there is the $185.5 billion figure from Momentum Works, the Singapore-based venture builder whose annual report has become the region's default citation. That number describes total trade, a broader basket than platform GMV, and it is the figure that travels. It gets quoted in boardrooms, government briefings, and keynote slides because it is big enough to impress and sourced enough to defend. Momentum Works has earned its authority through years of granular tracking. But authority is not audit. A widely cited estimate remains an estimate, and the methodology behind the extra $28 billion above platform GMV deserves more scrutiny than it typically receives at conferences. The third number complicates everything. The e-Conomy estimate puts the market at $191 billion. Now the spread is not methodological trivia. It is a structural disagreement about what ecommerce even is. Does it include services booked online? Groceries ordered through chat apps? Social commerce settled by bank transfer? Each definition adds billions, and each research shop has commercial reasons to prefer a particular frame. A venture builder wants a dynamic market. A platform-adjacent report wants a growing market. A seller of research wants a large market. The incentives are not sinister. They are simply never disclosed alongside the headline figure. Here is the uncomfortable game theory. Every participant in this market benefits from ambiguity except the people deploying capital based on it. A founder raising a Series B can claim to operate in a $191 billion market while reporting traction against a $157.6 billion denominator, and both claims are technically sourced. A regional fund underwriting Southeast Asia exposure cannot cleanly compare portfolio performance against a benchmark, because the benchmark is three different numbers wearing the same costume. Public market analysts covering Sea Limited or Grab face the same fog when sizing total addressable opportunity. The absence of a shared audit trail is not an accident of a young industry. It is an equilibrium that suits incumbents, because confusion favors whoever already holds the narrative. The practical fix is unglamorous. The region needs a common measurement convention, the way advertising eventually standardized impressions and viewability after years of chaotic self-reporting. That means agreement on what sits inside the ecommerce boundary, disclosure of methodology alongside every headline number, and some body, perhaps an industry association or a neutral research consortium, willing to publish a single reconciled estimate with its assumptions attached. None of this requires new technology. It requires a few influential players to accept a smaller, more honest number. That is precisely why it has not happened. The first Southeast Asian ecommerce firm to publish its market sizing with full methodological disclosure will quietly become the only source serious capital trusts.
More

Inside Taiwan’s NT$43.7 Trillion Wealth Machine: Decoding the Six Channels Holding the Island’s Centi-Millionaires

Taiwanese private wealth is scaling heights that make traditional banking models look like pocket change. When you have one hundred and eighteen thousand people sitting on investable assets above NT$100 million, controlling a staggering NT$43.7 trillion total, the mechanics of how that money moves change completely. We are past the era of standard retail wealth management. The market is staring down the 2026 horizon with a completely restructured liquidity map, where every single asset management channel tells a different story about where the ultra-rich park their fortunes. The underlying data points from the ground tell a raw, unvarnished story of aggressive regional expansion and targeted high-net-worth acquisition. Look at the Kaohsiung pilot zone alone, pulling in NT$728 billion, or map that against the broader island-wide footprint where 23,000 high-asset banking clients are currently active. These are not arbitrary figures tossed into a marketing deck. They represent the exact pressure points where domestic capital is being corralled, institutionalized, and aggressively competed for by traditional lenders and private banking desks alike. Wealth management in Taiwan has evolved from a passive deposit-gathering exercise into a high-stakes territorial game. As the centi-millionaire demographic expands toward the 2026 forecast, the real winners will not be the institutions with the most branches, but the ones controlling the hyper-specific asset channels that these heavy hitters actually trust. The commercial loop is tightening, leaving zero room for legacy banking bloat as private capital dictates the ultimate endgame for the island's financial sector.
More

Qatar’s Gas Play Hides the Solar Lie: Why 30% Capacity Won’t Move the Grid

The desert heat in Doha does not care about press releases. It cares about thermodynamics and contract law. Qatar has announced a 4,000 MW solar plan. The headline says 30% of total capacity. But look at the numbers. If solar provides 30% of the peak load, the math breaks. The grid is dominated by gas. The solar share of actual energy will be half the capacity target. This is not a minor rounding error. It is a fundamental disconnect between political ambition and physical reality. Here is the official story. The 4,000 MW plan is the centerpiece. The North Field expansion adds 142 mtpa of gas capacity. These two numbers are presented together. The industry subtext is different. The gas expansion secures long-term export deals. The solar project secures domestic baseload stability. But the grid is designed for gas. Solar is intermittent. You cannot dispatch sunlight. The 30% capacity claim ignores the load factor. At peak summer demand, solar output drops. You need gas backup. So solar contributes far less to total energy than its nameplate suggests. Consider the contracts. The North Field build-out is massive. It locks in infrastructure for decades. The solar contracts are complex. They involve storage and dispatchability. The grid operator must manage both. But the gas infrastructure is the anchor. The solar component is a hedge against rising costs. It is not a replacement. The 30% figure is a marketing tool. It signals green ambition. But the energy share will be roughly 15%. The difference is in the hours of sun versus the hours of demand. You cannot store that much energy cheaply at scale today. The supply chain landscape is clear. Qatar is hedging its bets. It is not transitioning to solar. It is maintaining gas dominance while adding solar as a cost mitigator. The 142 mtpa gas build-out is the real story. It ensures Qatar remains a top LNG exporter. The solar plan is secondary. It addresses domestic stability and ESG metrics. But it does not change the fundamental energy equation. The grid will run on gas. The solar percentage is a capacity metric, not an energy metric. Ignore the headline. Watch the gas contracts. That is where the value lies.
More